What is the real difference between new construction and resale here?
Here in Temecula, Murrieta, Menifee and Lake Elsinore, you can tour brand-new tracts and 1990s neighborhoods in the same weekend, sometimes on the same street. If you are still picking a city, start with our guides to Temecula, Murrieta, Menifee and Lake Elsinore. This post is about the decision itself: brand new from a builder, or a home somebody already lived in.
When I say resale, I mean any home that has been owned and lived in before. It could be 5 years old or 50. When I say new construction, I mean a home you buy from the builder, either finished and waiting (a quick move-in) or one you wait on while it is built.
| Question | New construction | Resale |
|---|---|---|
| Mello-Roos (CFD) special tax | Common on new tracts; read the Notice of Special Tax | Depends on the tract; older areas often have none, newer resales may |
| HOA dues | Common; the numbers are in the DRE public report | Varies; many older streets have none |
| Who you negotiate with | A builder with a set price sheet and its own contract | An owner, on a standard purchase agreement |
| What you can negotiate | Incentives, closing costs, rate buydowns, upgrades | Price, credits, repairs, closing date |
| Closing date | The builder's estimate, and it can slip | A date you set in the contract |
| Warranty | At least one year fit and finish under California law, plus the builder's own | None by law; an optional home warranty plan |
| Yard and extras | Often bare dirt in back; window coverings and fencing may cost extra | Usually finished, often with mature trees |
| Systems | New roof, HVAC and water heater | Depends on age; that is what the inspection is for |
Neither column wins on every line, right? So the rest of this guide walks through the lines that move your money the most.
Which costs more each month, a new build or a resale?
On the sticker price, it depends on the street. On the monthly payment, the new build often starts behind because of Mello-Roos and HOA dues. Let's run a hypothetical so you can see why.
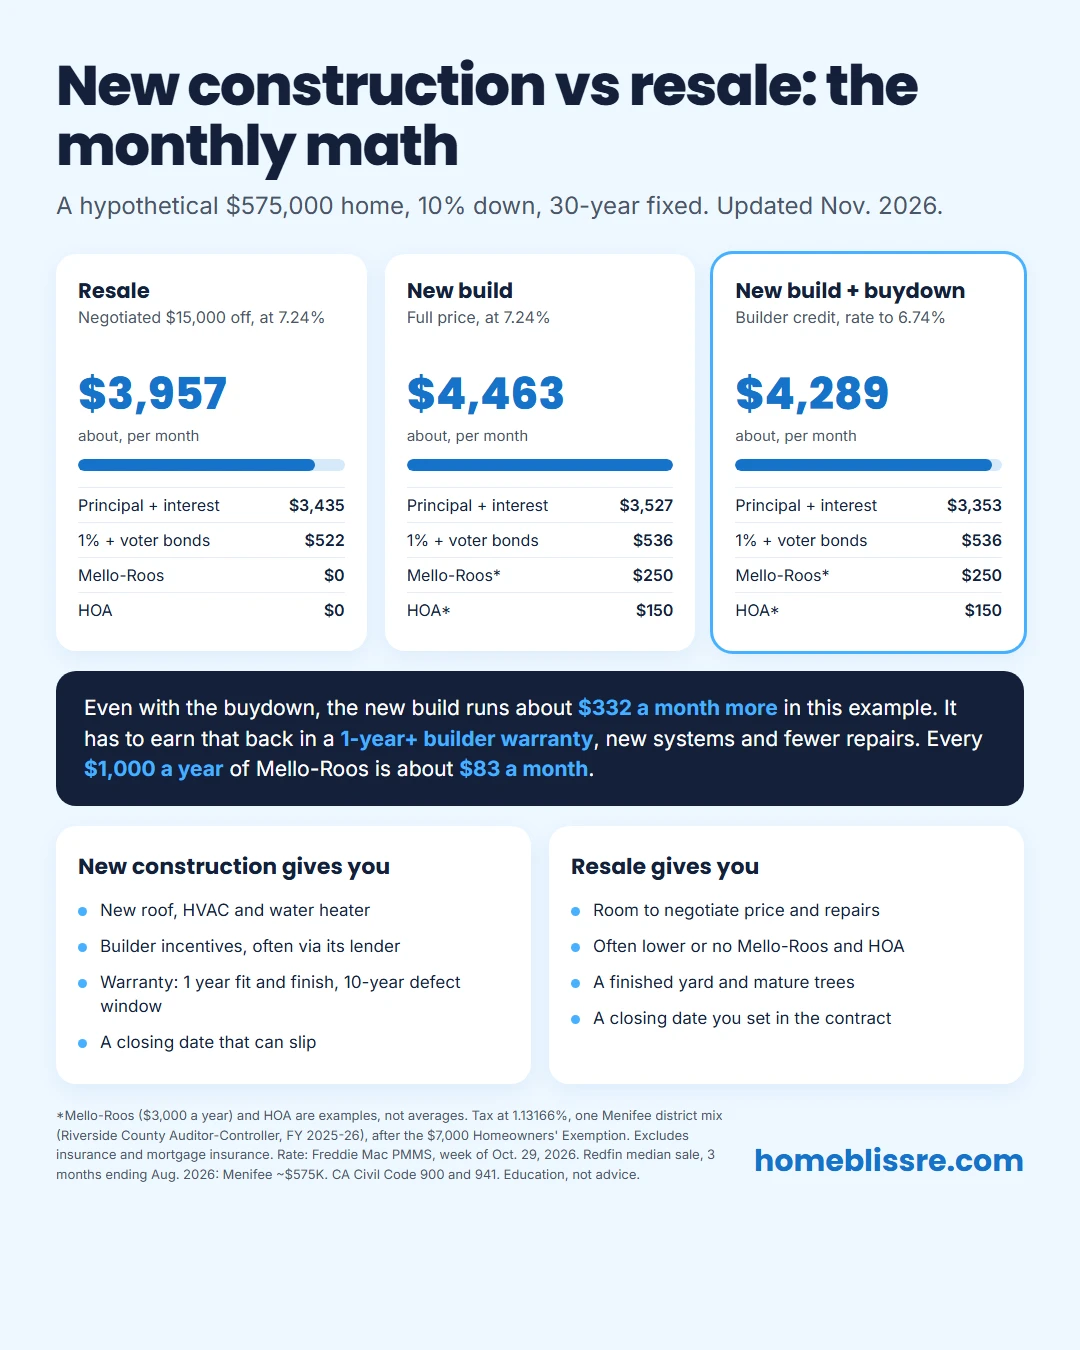
Say both homes are priced at $575,000, about Menifee's Redfin median sale price for the 3 months ending August 2026. You put 10% down on a 30-year fixed at Freddie Mac's 7.24% average for the week of October 29, 2026. The resale seller agrees to $15,000 off. The builder will not cut the price, but it offers a credit that buys your rate down half a point. The Mello-Roos and HOA amounts below are examples, not averages for any city.
| Monthly line (hypothetical) | Resale, negotiated to $560,000 | New build at $575,000, 7.24% | New build at $575,000, bought down to 6.74% |
|---|---|---|---|
| Principal and interest, 10% down | About $3,435 | About $3,527 | About $3,353 |
| 1% plus voter bonds at 1.13166%, after the $7,000 Homeowners' Exemption | About $522 | About $536 | About $536 |
| Mello-Roos, example of $3,000 a year | $0 | About $250 | About $250 |
| HOA dues, example | $0 | $150 | $150 |
| Subtotal before insurance and mortgage insurance | About $3,957 | About $4,463 | About $4,289 |
The 1.13166% is one common Menifee district mix from the Riverside County Auditor-Controller's FY 2025-26 rate table. Your parcel's mix can be different.
So in this example, even with the rate buydown, the new build runs about $332 a month more than the resale. That does not make the resale the better buy. The resale might need a new roof in a few years, and the new build's roof is new and under warranty. What it does show you is the size of the gap the new build has to earn back in lower repairs, lower energy bills and peace of mind. Plug in the real numbers from the tax bill, the Notice of Special Tax and the HOA budget, and the answer can flip.
Two more things. A resale in a tract built in the last 20 years can carry Mello-Roos too, so never assume older means none. And a lower price with a big Mello-Roos can cost more each month than a higher price without one. Our Mello-Roos lookup guide shows how to find the real amount for any address, and the Riverside County property tax guide explains the 1%, the bonds and the supplemental bill.
Are builder incentives worth more than negotiating on a resale?
Builders like to give you an incentive instead of cutting the price, because a lower price becomes a public comp for every home left in the tract. A resale seller has no tract to protect, so price is on the table. Here is what you can usually ask for on each side.
| Lever | New construction | Resale |
|---|---|---|
| Price | Hard to move, especially early in a phase | Negotiable, depending on the market and the home |
| Rate buydown | Common, often tied to the builder's preferred lender | Possible, as a seller credit you put toward points |
| Closing cost credit | Common, often tied to the preferred lender | Negotiable as a seller credit |
| Upgrades and lot | Design center credits, sometimes a break on a lot premium | What you see is what you get |
| Repairs | The builder's walkthrough list and warranty | Negotiated after your inspection |
| Transfer tax, escrow and title | Spelled out in the builder's contract | Negotiated in the purchase agreement |
A permanent rate buydown helps most if you keep the loan for years. A lower price helps if you might refinance or sell sooner, and it also lowers the assessed value your 1% tax is figured on. Mello-Roos does not change either way. So again, get the builder's offer in writing, then ask an outside lender to price the same home without it. Our Menifee new homes guide lists the builder rate offers we saw this fall, with dates, and the Temecula new construction guide runs a price cut against a buydown on a $735,000 home.
I am not going to tell you which one to take. It depends on how long you plan to stay and what the house in front of you needs.
How do timelines compare on new construction vs an existing home?
A resale closes on a date you write into the contract. A to-be-built home closes when the builder finishes, and the date in the builder's contract is usually an estimate. Rain, inspections and materials can push it. A quick move-in home sits in between: it is already built, so it can close on a timeline closer to a resale, but it is still sold on the builder's contract with the builder's disclosures.
If you have a lease ending, orders, or a home of your own to sell, timing can matter more than any incentive. Ask the builder what happens to your deposit and your rate lock if the home runs late, and get the answer in writing. On a resale, your agent can build the dates around your move.
On both, budget for the supplemental property tax bill. The Riverside County Assessor reappraises a home when it changes ownership or when new construction is completed, and that bill is mailed to you, not to your lender (Riverside County Assessor-County Clerk-Recorder, checked October 2026).
Do you need an inspection and a warranty on both?
Yes on the inspection, both times. On a resale, your inspector is your best tool to find what 20 or 30 years did to the roof, the plumbing and the HVAC, and the report is what you negotiate repairs from. The seller also fills out California's Real Estate Transfer Disclosure Statement (Civil Code 1102.6).
On a new build, the city inspects for code, which is the minimum. Ask the builder in writing whether your own inspector can come at pre-drywall and again before the final walkthrough. Some builders allow it with notice and some do not.
Warranties are where new construction pulls ahead. California requires builders to give a written fit-and-finish warranty of at least one year on things like cabinets, flooring, countertops and paint (Civil Code 900), and most defect claims under the same law can be brought within 10 years of substantial completion (Civil Code 941). A resale has no builder warranty. What you get is whatever you negotiate, plus what your inspection finds.
What about lot size, landscaping and the extras a model home leaves out?
The model home is dressed to sell. The home you buy may not come with the window coverings, the backyard, the fence or the upgrades you saw. Out here, a new build often comes with a finished front yard, usually low-water landscaping or mulch, and a bare dirt backyard. That is real money and real weekends before the house feels done.
- Lot. Compare the actual square footage of the lot, not the model's. Ask about lot premiums for corners, views or a bigger backyard.
- Finished extras. Price out backyard landscaping, fencing, window coverings and any appliances not included before you compare against a resale that already has them.
- Solar. Ask whether panels are included, financed or leased, and what that adds each month.
- What is next door. A new tract can sit next to open land that is already approved for more homes. Check the city's planning pages.
A resale usually hands you a finished yard and grown trees on day one. You trade that for older systems and a design you may want to update.
Can you bring your own agent when you buy from a builder?
Yes, and you should decide that before your first visit. The person in the sales office works for the builder. Many builders only work with your agent if the agent is with you, or registered for you, the first time you walk in or sign up online. Each builder sets its own rule, so ask before you go.
Your agent pulls resale comps so you know what a similar home sells for on the open market, reads the builder's contract and the Notice of Special Tax with you, and runs the incentive against a price cut with real loan numbers. For the full step by step, see our guide to buying new construction in Temecula. To see what is actually selling, read new homes in Murrieta, new homes in Menifee by price tier and new homes in Winchester.