Can you use a VA loan to buy a home in Riverside County?
Yes. The VA home loan is a federal benefit, so it works the same in Temecula, California, Murrieta and Menifee as it does anywhere in the country. VA does not lend the money. A private lender makes the loan, and VA guarantees part of it, which is why lenders can offer zero down and no monthly mortgage insurance.
Three things have to line up before a VA loan can close on a house here:
- You. You need a Certificate of Eligibility (COE). Your lender can usually pull it online, or you can request it yourself on VA.gov or by mail with VA Form 26-1880.
- Your budget. The lender checks your credit, your debt-to-income ratio and VA's residual income test. More on that below.
- The house. It has to appraise at or near the price and meet VA's Minimum Property Requirements, and you have to plan to live in it as your home.
For context on price, Redfin's median sale price for the three months ending August 2026 was about $735,000 in Temecula, $655,000 in Murrieta and $575,000 in Menifee, across all home types. If you are coming from Camp Pendleton, Temecula is about 30 miles from the Main Gate, Murrieta about 38 and Menifee about 51. Our Camp Pendleton BAH guide covers what your 2026 housing allowance roughly buys in each city.
Is there a VA loan limit in Riverside County in 2026?
Not if you have full entitlement. Since January 1, 2020, VA has not capped the loan amount for veterans and service members with full entitlement. VA says you do not have a loan limit as long as you can afford the loan and the appraisal supports the price. Your lender still sets the most it will lend you.
You generally have full entitlement if you have never used your VA benefit, or you used it and paid the loan off in full and sold the home, or a qualified veteran assumed your loan and substituted their entitlement for yours.
County limits still matter if you have partial entitlement, meaning a VA loan is still open on another home (a rental you kept after a PCS, for example). Then VA uses the county's conforming loan limit to figure out how much guaranty you have left. For 2026, Riverside County's one-unit limit is $832,750 (FHFA).
| Step (hypothetical veteran with $100,000 of entitlement still in use) | Amount |
|---|---|
| 25% of the 2026 Riverside County limit ($832,750) | $208,188 |
| Minus entitlement already in use | $108,188 remaining |
| Times 4: the loan size that remaining entitlement covers with zero down | About $432,750 |
| Buying at $655,000 (the Murrieta median): 25% of the $222,250 gap, a common lender down payment ask | About $55,560 |
That table is an illustration of the math on VA's loan limits page, not a quote. Your lender runs the real numbers from your COE.
How much is the VA funding fee in 2026?
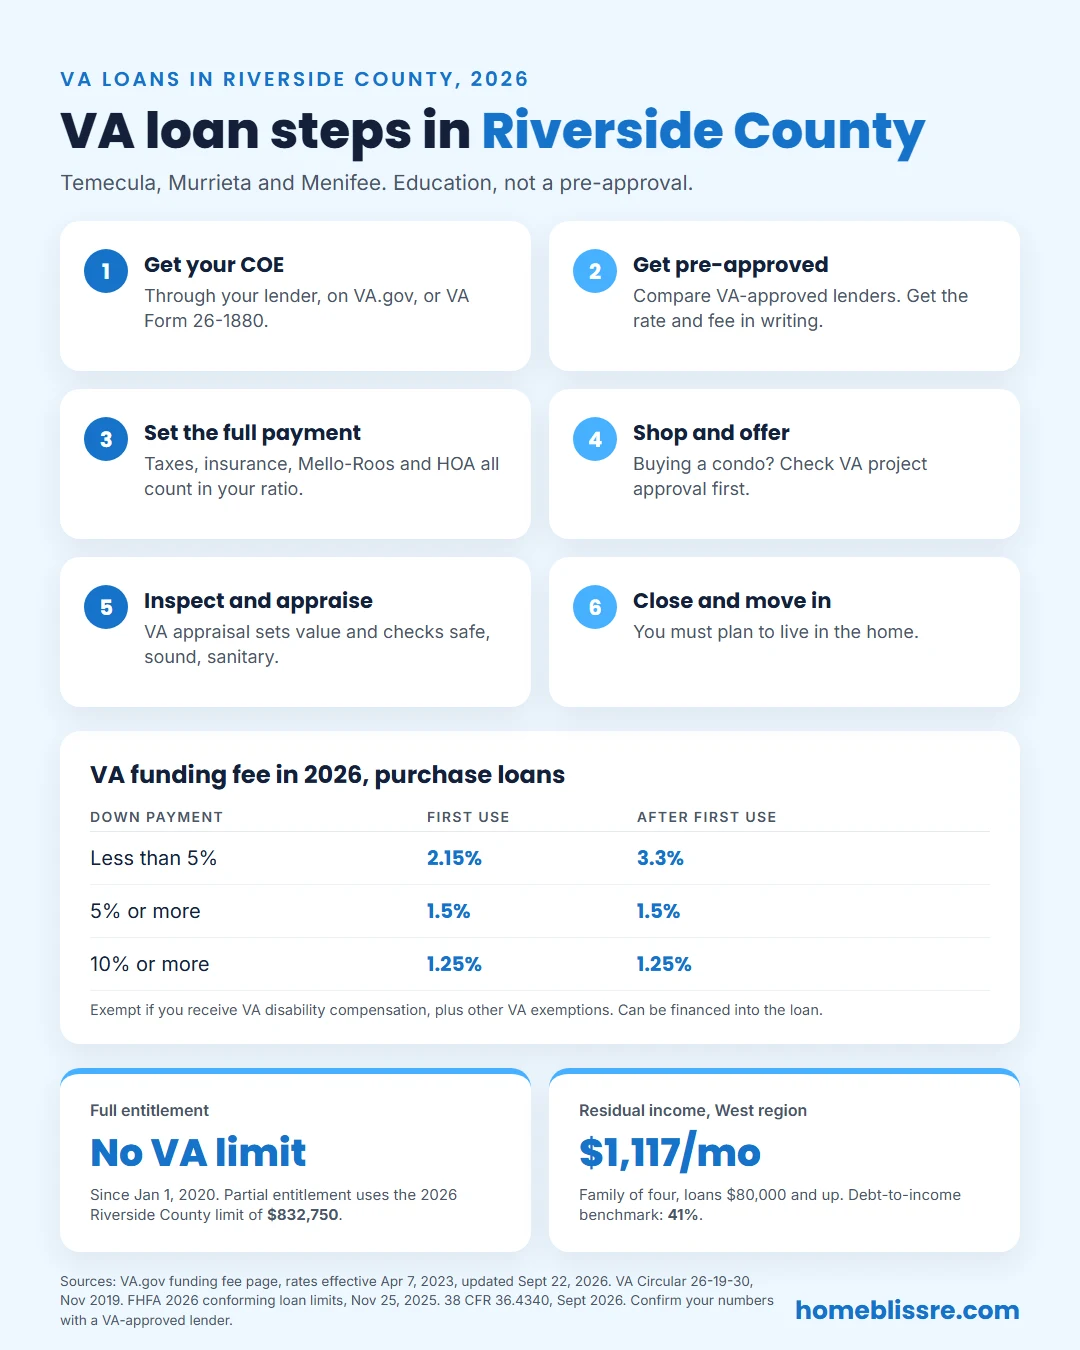
The funding fee is a one-time charge that keeps the VA loan program running. It is a percentage of the loan amount, and it depends on whether this is your first VA loan and how much you put down. These are VA's current rates for purchase and construction loans.
| Down payment | First use | After first use | Fee on a $655,000 loan, first use |
|---|---|---|---|
| Less than 5% | 2.15% | 3.3% | About $14,080 |
| 5% or more | 1.5% | 1.5% | Fee applies to the smaller loan |
| 10% or more | 1.25% | 1.25% | Fee applies to the smaller loan |
Source: U.S. Department of Veterans Affairs, funding fee rates effective April 7, 2023, page updated September 22, 2026. You can finance the funding fee into the loan. VA says it is the only fee you can roll in on a purchase; everything else is paid at closing or covered by seller credits.
You do not pay the funding fee at all if you:
- Receive VA compensation for a service-connected disability, or are eligible for it but receive retirement or active-duty pay instead.
- Receive Dependency and Indemnity Compensation as a surviving spouse.
- Are a service member with a proposed or memorandum rating saying you are eligible for compensation, dated before closing.
- Are on active duty and show proof of a Purple Heart on or before closing.
How much income do you need for a VA loan in Riverside County?
VA does not set a minimum salary. It uses two tests, and lenders look at both: your debt-to-income ratio, with 41% as the benchmark, and your residual income, the money left each month after taxes, the full house payment, maintenance, utilities and your other debts.
California falls in VA's West region, which has the highest residual income figures in the country. For loans of $80,000 and above, these are the monthly minimums from 38 CFR 36.4340.
| Household size | West region residual income, per month |
|---|---|
| 1 | $491 |
| 2 | $823 |
| 3 | $990 |
| 4 | $1,117 |
| 5 | $1,158 |
| Each additional member, up to 7 | Add $80 |
Two details matter here. Everyone in the household counts, even a spouse who is not on the loan. And for active-duty service members and military retirees who will keep using a nearby base's facilities, the rule reduces these figures by at least 5%. If your debt-to-income ratio is over 41% but your residual income beats the guideline by 20% or more, the regulation lets the loan move forward without extra justification.
The part buyers miss in this valley: the 41% ratio counts principal, interest, taxes, insurance plus homeowners association dues and special assessments. A Mello-Roos special tax or an HOA in a newer Menifee or Murrieta tract is part of your qualifying payment, so two homes at the same price can qualify very differently.
What does the VA appraisal check, and can you buy a condo?
A VA appraiser does two jobs. First, the appraiser sets the home's value, and VA sends a Notice of Value. If the price is higher than that value, the zero down benefit only covers up to the appraised value, so you either renegotiate, cover the gap in cash, or walk away under your contract terms.
Second, the appraiser checks the home against VA's Minimum Property Requirements. VA describes them as making sure the home is safe, structurally sound and sanitary. In practice that means things like a sound roof, working heat, safe water, a safe way to dispose of sewage, and no hazards that affect the people living there. Anything that fails shows up as a required repair on the Notice of Value, and it has to be fixed before closing.
The appraisal is not a home inspection. It is about value and minimum standards. A separate inspection, paid by you, looks much deeper, and it is worth having on any house.
Condos and some townhomes add one more step: the whole project has to be VA-approved, not just your unit. Search the community by name in VA's condo report lookup before you write an offer. If it is not listed, the HOA or your lender would have to submit it to VA for review, which adds time and is not guaranteed.
What costs go into a VA loan payment in Temecula, Murrieta and Menifee?
Zero down does not mean zero cost. Here is what to price out on any Southwest Riverside County house before you count on a VA loan to cover it.
- Principal and interest. Based on your lender's VA rate, not the 7.28% conventional benchmark.
- Property tax. California's base is 1% of the price, plus voter-approved bonds that vary by area. Our Riverside County property tax guide shows how to pull the real bill for an address.
- Mello-Roos. Many newer tracts carry a special tax on top of the 1%. It counts in your qualifying ratio.
- HOA dues. Common in the master-planned communities in all three cities. These count too.
- Homeowners insurance. Get a quote on the exact address early.
- The funding fee, unless you are exempt, usually financed into the loan.
- Closing costs. Title, escrow, recording, the VA appraisal fee and lender fees. Riverside County's documentary transfer tax is $1.10 per $1,000 of value, and who pays it is set in the purchase contract.
Should you also look at CalVet or an assumable VA loan?
They are two other paths, and each one fits different situations. This is how they work, not a recommendation.
CalVet Home Loans is California's own veteran home loan program, run by the California Department of Veterans Affairs. CalVet says any veteran can apply when buying an owner-occupied home in California, with at least 90 days of active duty (not counting training), a discharge under honorable conditions, and no current CalVet loan. There is no prior California residency rule. It offers 30-year fixed purchase loans, most with no down payment, and most CalVet loans include its own fire, hazard and disaster coverage. Compare its rate, fees and terms against a standard VA loan with your lender and with CalVet directly.
Assuming a seller's VA loan means taking over their existing loan, rate and balance. VA charges a 0.5% funding fee on an assumption unless you are exempt, and the lender or VA has to approve you. If you are an eligible veteran, you can substitute your entitlement so the seller gets theirs back. The catch is the gap: you pay the difference between the price and the loan balance, which can be large on a home bought a few years ago. Some listings advertise an assumable VA loan, so ask your agent and lender to run the numbers both ways.
What are the steps to buy with a VA loan in Riverside County?
- Get your COE. Through your lender, on VA.gov, or by mail with VA Form 26-1880.
- Get pre-approved with a VA-approved lender. Ask for the funding fee, rate and estimated closing costs in writing, and compare more than one lender.
- Set your full payment target. Include taxes, insurance, Mello-Roos and HOA, not just principal and interest.
- Shop and write offers. For a condo, check VA project approval first. Ask for seller credits toward closing costs where the market allows.
- Inspect and appraise. Order your own inspection. The VA appraisal sets value and lists any required repairs.
- Close and move in. VA requires that you plan to live in the home. If you have a 100% permanent and total rating, file for California's disabled veterans' property tax exemption with the county after you close.