Which first-time home buyer programs can you use in Riverside County right now?
Now, the honest answer depends on two things: which city the house sits in, and when you read this. Down payment money in this county runs out, gets refilled, and runs out again. So treat this guide as a map of what exists and how it works as of October 2026, then confirm current availability with the program and a participating lender before you count on any of it.
Riverside County Housing and Workforce Solutions (HWS) runs the county programs, CalHFA runs the statewide ones, and the federal loan types work the same in Riverside, California as they do in Temecula, Murrieta, Menifee or Lake Elsinore.
| Program | What it does | Status as of October 2026 |
|---|---|---|
| Riverside County PLHA FTHB | Up to 20% down payment, max $100,000, 0% deferred, forgiven after 30 years | Open in some cities only. $0 in Murrieta and 13 other areas (Bulletin #10, Aug 24, 2026) |
| Riverside County HOME FTHB | Up to 20% down payment, max $100,000, deferred, forgiven after 15 years | $64,679 left countywide; not usable in Temecula, Murrieta, Menifee or Lake Elsinore |
| CalHFA MyHome | Deferred junior loan, up to 3.5% (FHA) or 3% (conventional) | Listed as an active CalHFA program |
| CalHFA Dream For All | Shared appreciation loan, up to 20%, max $150,000, first-generation buyers | 2026 round closed March 16, 2026 |
| Riverside County MCC | Federal tax credit on 20% of mortgage interest | Funds exhausted, no new applications |
| FHA, VA, USDA loans | Low or zero down payment first mortgages | Available through approved lenders |
One more thing, right? None of these programs takes an application from you directly. The county and CalHFA both work only through approved lenders, so your first call is to a loan officer who is approved for the program you want.
How does Riverside County's down payment assistance work?
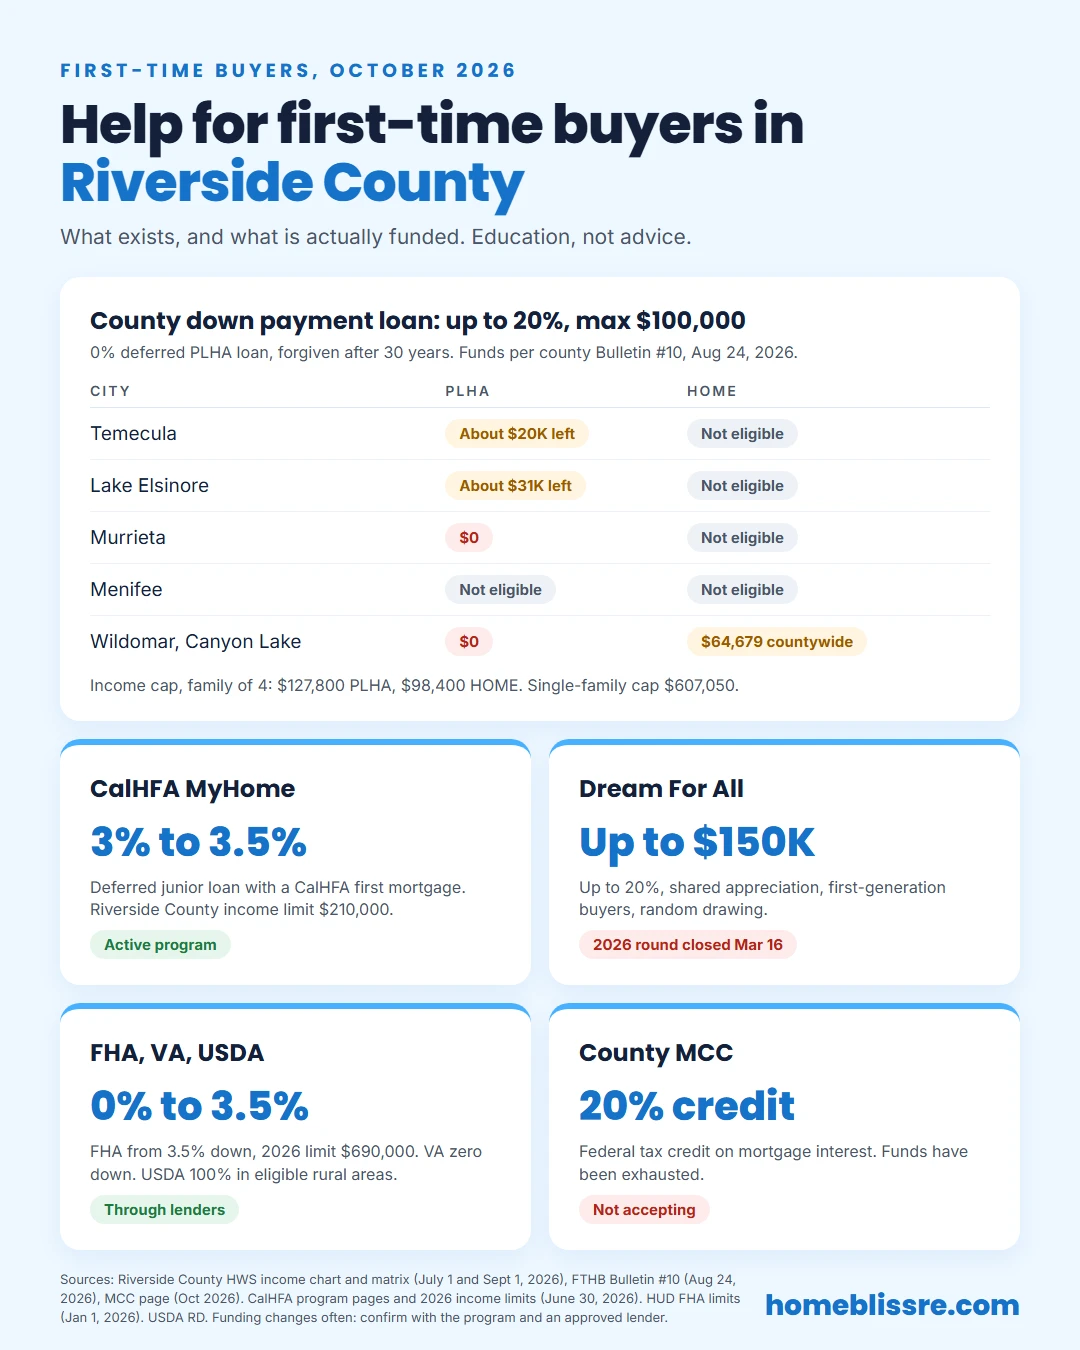
The county offers two first-time buyer programs, funded by HOME (a federal grant) and PLHA (a state housing fund). Both lend only what you need, up to 20% of the home's sales value and never more than $100,000. The money is a silent second loan with no monthly payment, and it is only due if you sell or do a cash-out refinance before the affordability period ends. After that period it turns into a grant. The PLHA packet adds that the loan is not interest bearing and has a $1,500 minimum.
| HOME FTHB | PLHA FTHB | |
|---|---|---|
| Income ceiling, household of 4 | $98,400 (80% of area median) | $127,800 (120% of area median) |
| Income ceiling, household of 2 | $78,750 | $102,240 |
| Converts to a grant after | 15 years | 30 years |
| Cities NOT eligible | Cathedral City, Corona, Hemet, Indio, Jurupa Valley, Lake Elsinore, Menifee, Moreno Valley, Murrieta, Palm Desert, Palm Springs, Perris, Rancho Mirage, Riverside, Temecula | Calimesa, Corona, Menifee, Palm Desert, Perris, Rancho Mirage, Riverside |
| Cap on a single-family home | $607,050 | $607,050 |
| Cap on a condo or townhome | $470,250 | $470,250 |
Source: Riverside County HWS income chart and program matrix, effective July 1, 2026, revised September 1, 2026. The appraisal cannot come in above those caps either.
A few rules catch people off guard. The home needs at least two bedrooms. Your back-end debt ratio tops out at 45% for HOME and 50% for PLHA. The county does not cover closing costs right now, it says so on its own page. And you must take the largest first mortgage you qualify for, so the county money only fills the gap that is left.
Is there still county money for Temecula, Murrieta, Menifee and Lake Elsinore?
This is the part most guides skip, so let's be straight about it. The county posts funding bulletins for its lenders, and the latest one we found, Bulletin #10 dated August 24, 2026, said the PLHA money "depleted quickly." Here is where our home cities stood on that date.
- Murrieta: PLHA at $0.00. HOME does not cover Murrieta. So no county down payment money was available here on that date.
- Temecula: about $20,197 of PLHA money left. That may cover one buyer, maybe none, depending on the house.
- Lake Elsinore: about $31,025 of PLHA money left.
- Menifee: not eligible for either county program, funded or not.
- Wildomar, Canyon Lake and San Jacinto: PLHA at $0.00. HOME does cover these cities, from the $64,679 left countywide.
Now look at the caps next to real numbers. Redfin's median sale price for the three months ending August 2026 was about $735,000 in Temecula, $655,000 in Murrieta and $575,000 in Menifee. The county's single-family cap is $607,050. So in Temecula and Murrieta, the typical house is already over the limit, and the program fits a smaller house, a condo or townhome under $470,250, or a home in an eligible unincorporated area.
The county issues a new bulletin whenever money is added or used up, including at the start of its fiscal year on July 1. Ask a county-approved lender to check the newest bulletin on the day you apply, because this table can be out of date in a week.
What do CalHFA MyHome and Dream For All offer in 2026?
CalHFA is the California Housing Finance Agency. It does not lend to you directly either. It works through approved loan officers, and its programs are the ones most first-time buyers in Southwest Riverside County actually end up using.
MyHome Assistance Program. This is a deferred-payment junior loan that sits behind a CalHFA first mortgage. With a CalHFA FHA loan it can be up to 3.5% of the purchase price or appraised value, whichever is less. With a CalHFA conventional loan it can be up to 3%. Payments are deferred until you sell, refinance or pay off the first loan. CalHFA's 2026 income limit for Riverside County is $210,000, effective June 30, 2026. On a $575,000 home, 3.5% is about $20,125, which covers the FHA minimum down payment.
California Dream For All. This is the one people call the "$150,000 program." It offers up to 20% for down payment or closing costs, not to exceed $150,000, for first-generation homebuyers, and it is picked by random drawing, not first come, first served. The catch is how you pay it back: when you sell, refinance or pay off the loan, you repay the original amount plus a share of the home's appreciation, 20% of the gain for a moderate-income buyer, or 15% for a buyer at or below 80% of area median income, in CalHFA's own examples. The 2026 registration window closed March 16, 2026, and vouchers went out May 20, 2026. The Dream For All income limit for Riverside County is $168,000. If you were waitlisted, keep checking your portal. If you missed it, watch CalHFA for the next round, since it is not guaranteed there will be one.
Good news if you are in Temecula or Lake Elsinore: the county's program matrix says its down payment loan can be combined with CalHFA. Your lender has to confirm the stack works for your file.
What about FHA, VA and USDA loans for first-time buyers?
These are not grants. They are first mortgages with small or zero down payments, and for a lot of buyers they matter more than any assistance program, because they do not run out of money.
- FHA. HUD says your down payment can be as low as 3.5% of the purchase price. The 2026 FHA loan limit for a one-unit home in Riverside County is $690,000. Ask your lender for the full monthly cost, including mortgage insurance.
- VA. If you served, a VA loan can mean zero down and no monthly mortgage insurance, with a funding fee unless you are exempt. Our VA loan guide for Riverside County walks through the 2026 funding fee, entitlement and residual income.
- USDA. USDA's Section 502 Guaranteed Loan offers 100% financing in eligible rural areas for households earning no more than 115% of the area median. Eligibility goes by address, so check the exact property on USDA's eligibility map before you count on it.
CalHFA also offers its own FHA, VA, USDA and conventional first mortgages, which is how the MyHome loan gets attached. Compare a CalHFA package against a regular FHA or VA loan from more than one lender before you decide.
Is the Mortgage Credit Certificate still available in Riverside County?
Not right now. The county's MCC page says MCC program funds have been exhausted and applications are no longer being accepted.
For context, an MCC let a qualified buyer take a federal tax credit equal to 20% of the mortgage interest paid each year, which also helped some buyers qualify for a bigger loan. It could not be paired with bond-backed loans such as CalHFA or CalVet. If the county gets a new allocation from the state, it would be announced on that page, so ask your lender whether any MCC issuer covers the area where you are buying.
What should a first-time buyer budget for besides the down payment?
Assistance programs help with the down payment. They do not make the house cheaper to own each month, and the county is not covering closing costs right now. Plan for these too:
- Closing costs. Lender fees, title, escrow, appraisal and recording. Riverside County's documentary transfer tax is $1.10 per $1,000 of value, and the purchase contract sets who pays it.
- The interest rate. Freddie Mac's 30-year fixed average was 7.28% the week of October 1, 2026. Your rate depends on the loan type, your credit and your lender.
- Property tax and Mello-Roos. California starts at 1% of your purchase price, plus voter bonds, plus any Mello-Roos in newer tracts. Our Riverside County property tax guide shows how to pull the real bill for an address before you offer.
- HOA dues, insurance and repairs. The county's PLHA program also requires a one-year home warranty, which is one more line on the closing statement.
This guide is education, not lending, legal or tax advice. Program terms, limits and funding change often, so talk to an approved lender and confirm current availability with the county or CalHFA before you make an offer.